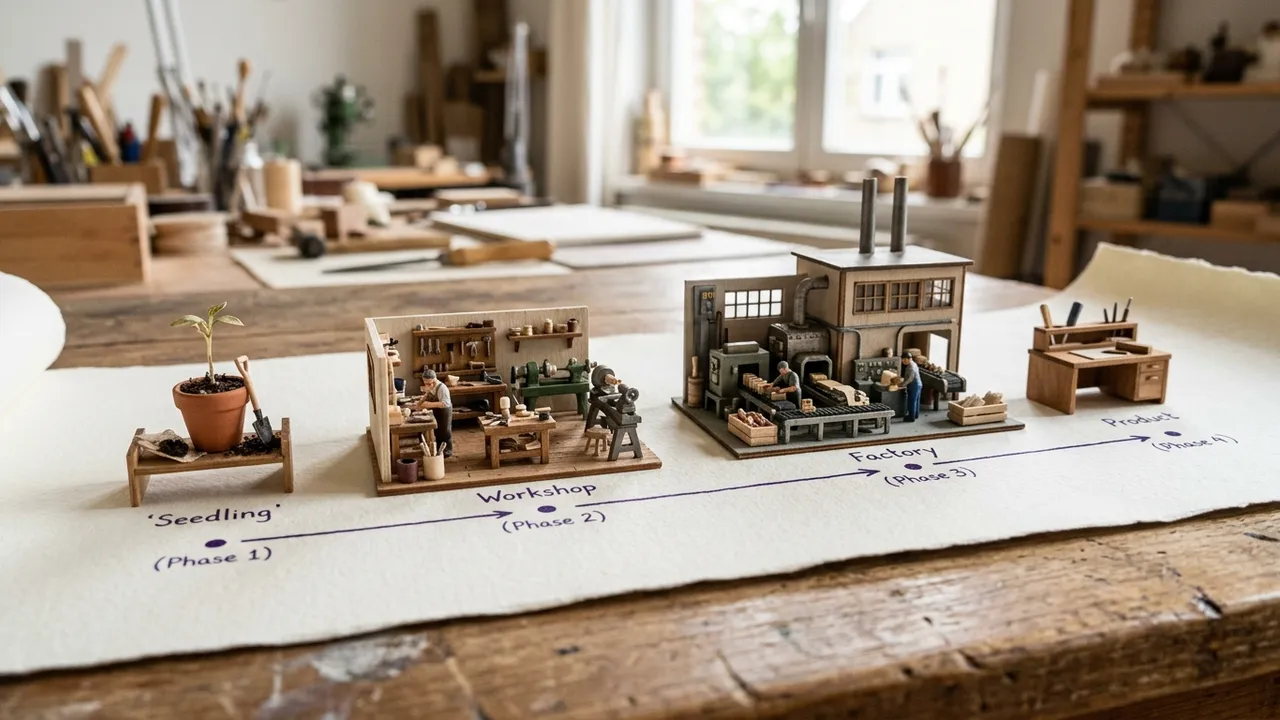
Private equity means equity investment in companies that are not listed on a stock exchange. It splits by company stage: seed for a project, venture capital for a young innovative company, growth capital for a profitable SME that is expanding, buyout capital when the shareholders change.
What is private equity?
It is the umbrella term. A private equity fund buys shares in a company that is not listed, then sells them years later. Gimv, a Belgian investor, Noshaq, the Liège provincial "invest" (a regional public-private investment company), and Theodorus, a seed fund linked to the ULB university, all do private equity. They do not finance the same company.
Which fund for which company stage?
| Stage | Target company | Risk for the fund | What the fund looks at first | What to do |
|---|---|---|---|---|
| Seed | Project or spin-off, product in development | Very high | Team, technology, intellectual property | Approach a seed fund (Theodorus: first ticket €250,000) |
| Venture capital | Young innovative company, first revenue | High | Traction, market, ability to raise later rounds | Plan for several rounds, not one |
| Growth capital | Profitable SME funding a new step | Moderate | Profitability, investment plan, management | Build the file with your bank (ORSA: €500,000 to €2.5M) |
| Buyout capital | Company changing shareholders | Moderate, debt included | Cash flow, ability to repay the acquisition debt | Set up the acquisition holding before knocking on doors |
Funds specialise in one or two stages. A university seed fund will not look at the buyout of a construction SME. A buyout fund will not finance a pre-clinical biotech.
What is the difference between venture capital and growth capital?
Profitability. Venture capital finances a company that burns cash; growth capital finances one that already generates it.
A venture fund knows that some of its holdings will fail. It makes up for them with the ones that do very well. For the founder, that shows up in two ways:
- a significant equity stake, with protective rights (preference shares, anti-dilution);
- an expected trajectory: further rounds, then a sale.
Growth capital takes a minority stake in an SME that works and wants to move up a level: a new production line, an acquisition, exports. Its equity strengthens the balance sheet, which lets the bank lend more. I saw this mechanism from the inside, in the business lending department of a Namur bank between 2009 and 2017: a file that had been turned down came back to committee a few months later, once the fund had come into the capital.
Who comes in before the funds?
Business angels, most of the time. They invest their own money, earlier and in smaller amounts than funds. Broadly speaking, they belong to private equity. In practice, their round often comes before a seed fund such as Theodorus, and they sign the next shareholders' agreement with it.
A trap I have seen more than once when reading agreements: the business angel secures rights in the first round that the fund arriving next insists on matching. The founder ends up renegotiating clauses they thought were settled. It is not illegal; it is mechanical. Better to know it before signing with the first investor.
Why does the stage change the contract?
Because risk is paid for in clauses. A venture fund that accepts losses on part of its portfolio protects its winners with preference shares and anti-dilution. A growth fund facing a profitable SME more often settles for a board seat and an exit timetable. Same percentage, two very different agreements: the page on anti-dilution and ratchet clauses details what the first one costs.
Can an SME avoid dilution?
Yes, with quasi-equity. ORSA publishes a Smart Bond, a non-dilutive subordinated loan over 5 to 10 years, with a return partly tied to EBITDA. A subordinated loan is repaid after all other debts. You keep 100% of your shares, but you pay a higher rate.
What happens at each venture round?
Rounds follow milestones: seed, Series A, Series B. Each round dilutes existing shareholders. A founder at 100% who gives up 20% at seed then 25% at Series A keeps 60% (100 × 0.8 × 0.75). That is before the employee option pool, often required along the way.
And buyout capital?
Here, the money does not grow the company. It pays a seller.
The deal usually rests on an acquisition holding company that combines the buyer's own funds, bank debt and a fund's investment. The name changes with the buyer: MBO for managers, MBI for an outside manager, OBO for the owner themselves. ORSA lists buyouts and succession among its targets; Sambrinvest mentions SMEs in succession in the Charleroi area.
Wallonia, Brussels, Flanders: four things to check before writing
First, place your stage in the table. Then my checklist, to tick off on the fund's website before you write to it:
- does the stage it targets match yours, not the stage you hope to reach?
- does your need fall within the published ticket?
- is your registered office in its area (province for an invest, region for a public body)?
- does the fund have an end date that constrains its exit?
In Wallonia, the provincial invests cover everything from start-up to succession: Noshaq publishes "from start-up to established SME", Sambrinvest lists start-ups, growing SMEs and SMEs in succession. In Brussels, finance&invest.brussels (the Brussels-Capital Region's public financing body) invests up to €5M in an SME, as co-investment. In Flanders, the public body is PMV; I have not surveyed it. For a deep tech start-up, the page on funding a biotech in Belgium sets out the path. For everyone else, the ranking of investment funds for SMEs lists nine funds with ticket, area and instruments.
Comparator
Compare investment funds side by side.
Compare now →
Frequently asked questions

From 2009 to 2017, Cédric spent eight years in the corporate lending department of a Belgian bank in Namur, on the side that turns files down and writes the covenants. He then became financial controller at an industrial SME in Hainaut just as a provincial invest took a stake in its capital. Based in Gembloux, he rereads the terms published by Walloon and Brussels funds and invests every month.