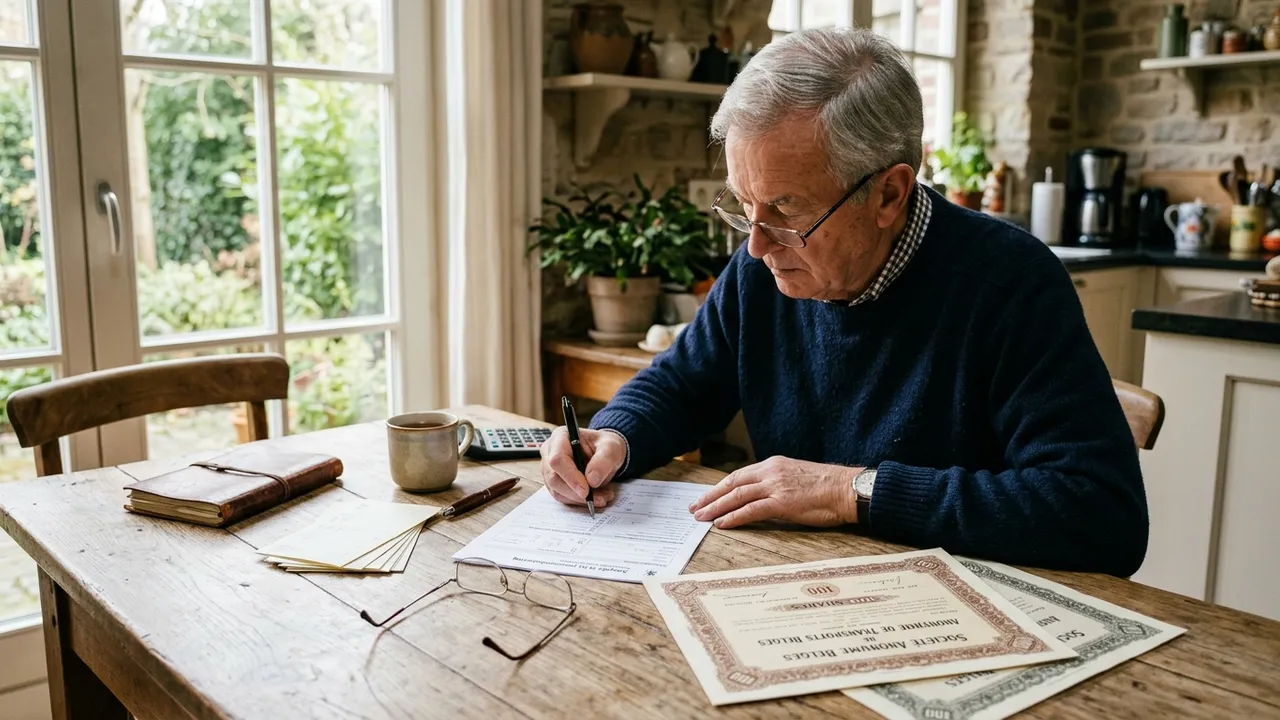
The start-up and scale-up tax shelter gives an income tax reduction to individuals who subscribe for new shares in a small company: 30% or 45% if it is under 4 years old, 25% if it is a growth company aged 5 to 10. The company can raise up to €500,000 or €1,000,000 this way, depending on the scheme.
My argument fits in one line: the tax shelter exists to bring private individuals into a round. Funds get nothing from it. It lowers the net price a business angel pays for the same stake, and nothing more.
What is the start-up tax shelter?
A federal tax incentive run by the SPF Finances (the Belgian federal tax administration). It targets the individual who subscribes for new shares, at incorporation or in a capital increase. Buying existing shares from a partner does not qualify.
There are two schemes. The start-up tax shelter covers small early-stage companies under 4 years old. The scale-up tax shelter covers small growth companies from their 5th to their 10th year inclusive. Both share the same per-investor ceiling.
| Criterion | Start-up tax shelter | Scale-up tax shelter |
|---|---|---|
| Target company | Small early-stage company, under 4 years old | Small growth company, 5 to 10 years old |
| Timing of subscription | At incorporation or in a capital increase within 4 years | In a capital increase from the 5th to the 10th year inclusive |
| Investor's tax reduction | 30% (small company) or 45% (micro-company) | 25% |
| Ceiling per investor | €100,000 per year, shared by both schemes | €100,000 per year, shared by both schemes |
| Ceiling raised by the company | €500,000 | €1,000,000 |
| Holding period | 48 months | 12 or 48 months depending on the condition |
| Annual certificate | Form 281.85 | Form 281.88 |
The per-company ceilings were doubled for subscriptions from 1 January 2021, according to the SPF Finances. The detailed conditions (size, growth, excluded activities) are on the SPF Finances pages for early-stage companies and growth companies.
What tax reduction does the investor get?
The reduction applies to the amount subscribed, at the scheme's rate. In percentages, the net outlay varies a lot depending on the company. A worked example, for the same €20,000 investment, using only the published rates:
| Company | Rate | Tax reduction | Investor's net outlay |
|---|---|---|---|
| Micro-company under 4 years old | 45% | €9,000 | €11,000 |
| Small company under 4 years old | 30% | €6,000 | €14,000 |
| Small growth company, 5 to 10 years old | 25% | €5,000 | €15,000 |
| Annual ceiling reached (€100,000 in a micro-company) | 45% | €45,000 | €55,000 |
For the start-up, the reading is straightforward. A business angel weighing two comparable deals pays €4,000 less for the same stake in the micro-company than in the scale-up. That gap comes up in the negotiation, even if nobody says it out loud.
The €100,000 ceiling applies per investor per year. Spouses and legal cohabitants are each entitled to it. A couple can therefore, in principle, subscribe €200,000 in the same year with the reduction, within limits your tax adviser will check against your situation.
45%
Maximum reduction (micro-company under 4 years old)
€100,000
Ceiling per investor per year
€1M
Ceiling raised by a scale-up
The serious objection: the reduction does not change the risk
This is the case against, and it is fair. Investing in a start-up carries a high risk of total loss. A 45% reduction does not lower that risk: it lowers the loss if the company fails, to 55% of the stake. An individual who invests for the tax break rather than for the project has already got the analysis wrong.
There is a second, more technical trap. The reduction can be partly clawed back if the conditions stop being met during the required period: 48 months for a start-up, 12 or 48 months depending on the condition for a scale-up. A quick resale, a capital reduction or a poorly planned restructuring can cost the investor part of the benefit. The founder is the one who will have to explain it to the business angels.
What conditions apply to the company?
The company carries most of the paperwork, and it is the company that can make its investors lose the benefit.
The obligations, as the SPF Finances describes them:
- check that it meets the conditions before announcing the tax shelter: small or micro-company size, age, and the other conditions set out in the SPF Finances FAQs and circulars;
- issue a certificate for each investor every year, form 281.85 for a start-up, 281.88 for a scale-up;
- send a copy to the administration before 31 March, via Belcotax-on-web or by e-mail to the relevant department;
- inform investors of the conditions for keeping the benefit and of the holding period.
Three mistakes keep coming up in the rounds I have seen:
- promising the reduction to a director of the company, when directors investing in the company where they hold their mandate are excluded;
- going over the company's fundraising ceiling, €500,000 or €1,000,000 depending on the scheme;
- forgetting that the reduction can be partly clawed back if the conditions are no longer met.
The first is the most frequent. A co-founder who puts fresh money into a capital increase is not entitled to it if he or she is a director. A relative with no mandate is.
The letter to send each business angel
Before the subscription, not after. I have seen rounds where the investor only discovered the holding period when trying to sell. A one-page letter prevents that misunderstanding, and it fits in five lines:
- the scheme used, start-up or scale-up, and why the company qualifies;
- the reduction rate that applies to the investor: 45%, 30% or 25%;
- the amount subscribed, with a reminder of the €100,000 annual ceiling across all deals;
- the holding period, 48 months or 12 to 48 months depending on the condition, and what triggers a partial clawback;
- the company's commitment to send the 281.85 or 281.88 certificate every year, with a copy to the administration before 31 March.
Point 3 matters more than it seems. An investor who has already subscribed elsewhere during the year may have used up part of the ceiling, and it is up to them to check.
An argument in a mixed round, not a source of funding
Back to the argument. The tax shelter does not concern funds themselves: a seed fund, an invest (a Walloon provincial investment company) or a private fund receives no reduction. It can however flow through certain intermediary vehicles provided for by law, such as an approved crowdfunding platform or a starter fund, which open it up to individuals.
In a round combining a fund and business angels, it makes the individuals' participation more attractive at the same valuation. It therefore pairs well with a seed fund or an invest coming in. That is the most common set-up in the seed rounds described in our article on funding start-ups and scale-ups.
One detail I always check in a term sheet: the order of operations. If the fund requires a single capital increase, and the business angels subscribe alongside it, each receives a certificate for their share. If part of the round goes through a sale of existing shares, that part qualifies for nothing. The difference is settled when the term sheet is drafted, not after signing.
Wallonia, Brussels, Flanders: the same scheme everywhere
The tax shelter is federal. Rates, ceilings and certificates are identical in Liège, Brussels and Ghent. From one region to the next, only the public bodies co-investing alongside individuals change:
| Region | Public co-investment body | Published ticket (surveyed on 15.10.2026) |
|---|---|---|
| Wallonia | Wallonie Entreprendre (the Walloon Region's public financing body) and the provincial invests (Noshaq, Sambrinvest, Namur Invest, Invest.BW, IMBC) | Namur Invest: €100,000 to €2.5M in general; Invest.BW: up to €2.5M in total; others: not published |
| Brussels | finance&invest.brussels | Up to €5M for SMEs, as co-investor |
| Flanders | PMV | Outside the main scope of this site |
For a Walloon start-up putting together a €500,000 round, the tax shelter draws in individuals and the provincial invest tops it up. Our ranking of SME funds sets out the terms each player publishes.
The nuance: a good tool, badly sold
The tax shelter works. It lowers a business angel's net outlay by 25% to 45%, which is far from marginal on a €20,000 ticket. But it is often sold badly, as a tax break with a start-up attached. Pitched that way, it attracts investors who will walk at the first delay.
My advice to founders: check eligibility before mentioning it, work out the net outlay for each investor, set out the holding period in writing, and promise nothing to a director. For the details of your own case, have the structure checked by your accountant before you open the round.
Comparator
Compare investment funds side by side.
Compare now →
Frequently asked questions

From 2009 to 2017, Cédric spent eight years in the corporate lending department of a Belgian bank in Namur, on the side that turns files down and writes the covenants. He then became financial controller at an industrial SME in Hainaut just as a provincial invest took a stake in its capital. Based in Gembloux, he rereads the terms published by Walloon and Brussels funds and invests every month.